Dynamic Currency Conversion Explained: Avoid Costly Markups
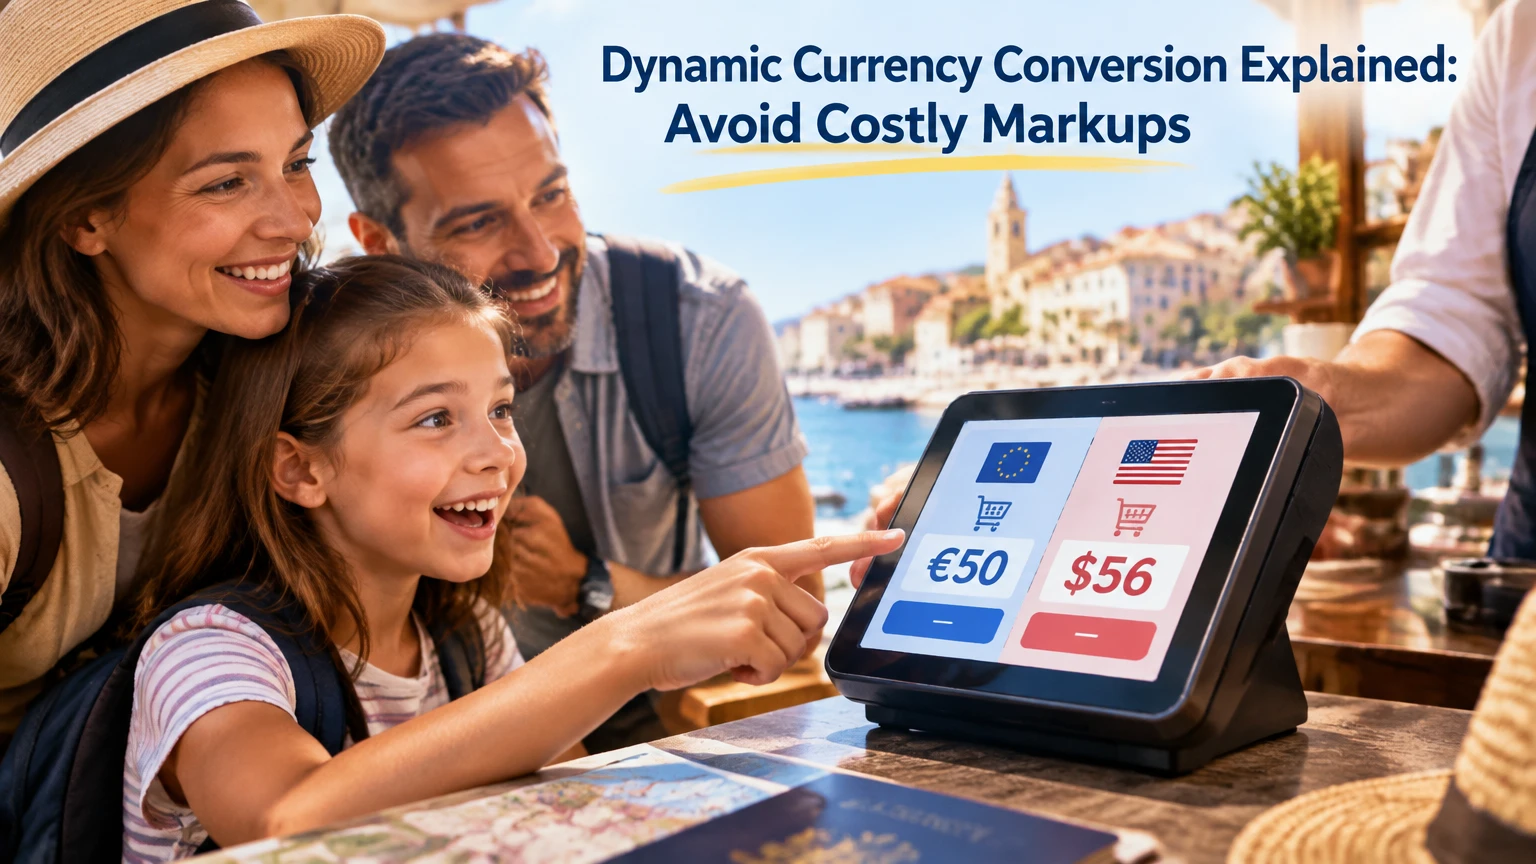
Dynamic Currency Conversion, or DCC, lets an international cardholder pay in their home currency at a foreign merchant or ATM instead of the local currency. The displayed amount feels predictable, but a DCC provider usually embeds its own exchange-rate markup, so choosing local currency generally gives the card network and issuing bank control of the conversion.
Key Facts at a Glance
- Dynamic Currency Conversion converts a foreign purchase or cash withdrawal into the cardholder’s home currency before final settlement.
- The merchant, ATM operator, payment processor, or DCC provider usually determines the offered exchange rate.
- Typical DCC markups are often around 3%-12%, although the exact premium varies by provider, merchant, country, and transaction type.
- Selecting local currency normally sends the original transaction amount through the card network for later conversion.
- A card with no foreign transaction fee can still produce a poor result when the cardholder accepts DCC.
- DCC is optional in a properly presented transaction, and the customer should see both currencies, the exchange rate, and the applicable markup before consenting.
What Is Dynamic Currency Conversion?
Dynamic Currency Conversion is a payment option that converts a foreign-currency card transaction into the cardholder’s billing currency at the point of sale or withdrawal. The terminal or ATM identifies a potentially eligible foreign card, presents two currencies, and allows the cardholder to accept the merchant’s conversion or continue in local currency.
DCC is not the same as a card issuer’s normal foreign-exchange process. With local-currency billing, the merchant submits the original amount, such as 10,000 Japanese yen, and Visa, Mastercard, or another applicable network helps determine the later conversion. With DCC, the merchant-side provider calculates and locks the home-currency amount before authorization.
The service has a legitimate convenience benefit. A traveler can see the approximate account charge immediately, avoid mental arithmetic, and record an expense in a familiar currency. The trade-off is reduced control over the exchange rate, because the merchant-side conversion may include a sizeable spread.
Who can receive a DCC offer?
International Visa and Mastercard cardholders are common DCC targets, although eligibility depends on the terminal, acquirer, processor, card currency, and local rules. DCC can apply to credit cards, debit cards, prepaid cards, and some commercial cards when the payment system recognizes a foreign billing currency.
A domestic card normally does not receive a DCC prompt because the merchant currency and card currency already match. A foreign card can still fail to trigger DCC because the terminal lacks the feature, the provider does not support the card brand, or the transaction runs through an offline or restricted flow.
How Does Dynamic Currency Conversion Work?
Dynamic Currency Conversion follows a short payment sequence: card identification, currency detection, rate quotation, customer choice, authorization, and settlement. The key decision occurs before authorization, when the terminal displays the local amount and the proposed home-currency amount.
The six-stage transaction flow
- Card identification: The terminal reads payment data that identifies the card program and issuing market. The BIN, or Bank Identification Number, helps payment systems infer the card’s country or billing currency.
- Currency eligibility check: The processor checks whether the card appears eligible for a home-currency offer. BIN recognition identifies a likely currency, but it does not independently prove the cardholder’s exact billing currency.
- Rate quotation: The DCC provider calculates a home-currency amount using its rate, which may include a disclosed markup or spread.
- Choice presentation: The terminal or ATM displays the local amount, converted amount, exchange rate, and, where required, the markup or rate difference.
- Customer selection: The cardholder chooses local currency or the offered home currency. The selection should be explicit, not inferred from a contactless tap or a hidden default.
- Authorization and settlement: The selected currency is authorized. If local currency is chosen, the card network and issuer generally perform the later conversion; if DCC is chosen, the home-currency amount is sent as the transaction amount.
DCC therefore changes who controls the conversion and when the rate becomes fixed. It does not eliminate foreign exchange, because every cross-currency transaction still needs a rate somewhere in the payment chain.
What does the terminal display?
A compliant DCC prompt should make the choice readable rather than burying it behind color, button position, or ambiguous wording. Look for:
- The purchase amount in local currency
- The proposed amount in the home currency
- The exchange rate used
- The markup, commission, or rate comparison where applicable
- A clear choice between local currency and home currency
- Evidence of the selected option on the receipt
A green “accept” button is not proof that DCC is beneficial. Terminal layouts vary, and some devices use the most visually prominent button for convenience rather than economics. Read the currency labels, not the color.
Where Does DCC Appear?
DCC occurs through physical terminals, ATMs, and online payment flows. The customer experience differs by channel, but the economic principle remains similar: a merchant-side or gateway-side party offers to convert the transaction before the card issuer performs its normal conversion.
| Channel | Typical transaction | Conversion prompt | Main risk |
|---|---|---|---|
| Retail POS | €120 clothing purchase in France | EUR or USD | High rate spread hidden in a familiar amount |
| Hotel terminal | ¥80,000 room bill in Japan | JPY or card currency | Large bill magnifies a modest percentage |
| ATM | 50,000 Thai baht withdrawal | THB or home currency | DCC plus operator fee plus issuer fee |
| Online checkout | £250 software or hotel booking | GBP or USD | Currency selector may default to visitor currency |
| Payment wallet | Foreign merchant processed through a wallet | Merchant or wallet currency | Conversion responsibility may be unclear |
How does DCC work at an ATM?
An ATM DCC offer converts the requested cash withdrawal into the cardholder’s home currency before the transaction reaches the issuing bank. The screen may show the local cash amount, a converted debit amount, the exchange rate, and a choice such as “with conversion” or “without conversion.”
Rejecting DCC does not make the withdrawal free. The ATM operator can still charge a fixed access fee, the card issuer can apply a cash-advance or foreign transaction fee, and the network can apply its own rate. Declining DCC only preserves the normal local-currency conversion route.
For example, a 300-euro withdrawal could produce three separate costs:
| Cost component | Example amount | Charged by | Applies when |
|---|---|---|---|
| Cash requested | €300 | ATM dispensing bank | Every withdrawal |
| ATM access fee | €5.00 | ATM operator | Operator-specific |
| DCC markup | 7% of converted value | DCC provider | Only if DCC accepted |
| Issuer cash fee | 3% or $10 minimum | Card issuer | Card-contract specific |
Independent ATM networks can present DCC frequently, but no brand-wide rule guarantees that every machine from a particular operator will use the same prompt or markup. Photographing the screen before acceptance creates useful evidence if the amount later appears incorrect.
Is online checkout conversion always DCC?
Online currency conversion is not always formally classified as DCC, but it can produce a similar result when a merchant or payment gateway converts the price into the shopper’s home currency. The important question is who sets the rate and which currency appears in the final authorization.
A Japanese retailer might display ¥25,000 and then offer approximately US$170. If the shopper selects dollars, the retailer or gateway controls that conversion. If the shopper keeps yen, the card network and issuer normally process the foreign-currency transaction instead.
Before paying online, inspect the currency selector, checkout summary, terms, and card statement preview. A website’s use of a familiar currency can improve comprehension while still adding a spread that is not visible as a separate fee.
How Much Does DCC Cost?
DCC commonly costs more than local-currency billing because the provider builds compensation into the exchange rate. A typical practitioner range is 3%-12% above a competitive reference rate, but actual pricing varies substantially and can be lower or higher.
Suppose the competitive conversion for a purchase is $100. The cost effect of different DCC markups would be:
| DCC markup | Home-currency amount | Extra cost versus $100 | Difference on a $1,000 purchase |
|---|---|---|---|
| 0% | $100.00 | $0.00 | $0.00 |
| 3% | $103.00 | $3.00 | $30.00 |
| 7% | $107.00 | $7.00 | $70.00 |
| 12% | $112.00 | $12.00 | $120.00 |
The calculation is straightforward: competitive converted amount multiplied by 1 plus the markup percentage. A card issuer may add a separate foreign transaction fee to local-currency transactions, so the correct comparison is not “DCC fee versus zero.” It is DCC’s embedded spread plus any issuer charges compared with the network rate plus the issuer’s applicable charges.
Does DCC avoid foreign transaction fees?
DCC does not reliably avoid foreign transaction fees. Some issuers define a foreign transaction by where the merchant is located or how the transaction is routed, not only by the currency shown on the statement. A purchase displayed in US dollars can therefore still attract an issuer fee from a foreign merchant.
| Charge type | Typical range | Primary decision-maker | DCC effect |
|---|---|---|---|
| DCC exchange spread | 3%-12% typical | Merchant-side provider | Added when home currency is selected |
| Foreign transaction fee | 0%-3.5% typical | Card issuer | May still apply |
| ATM operator fee | $0-$10 typical | ATM owner | Usually independent of DCC |
| Cash advance fee | $5 minimum or 3%-5% | Card issuer | Depends on card and withdrawal |
| Network conversion spread | Often below DCC spread | Card network and issuer | Used when local currency is selected |
The best comparison uses the card’s fee schedule, not a terminal’s promise. A zero-foreign-transaction-fee card usually makes local-currency billing especially attractive because the issuer removes one of the main costs of paying abroad.
DCC Versus Local-Currency Billing
Local-currency billing is generally the better default for travelers because it preserves access to the card network’s conversion process and avoids the merchant’s optional rate. DCC can still provide a valid budgeting benefit when immediate home-currency certainty matters more than minimizing the transaction cost.
| Decision factor | DCC, home currency | Local-currency billing |
|---|---|---|
| Rate setter | Merchant, acquirer, or DCC provider | Card network and issuer process |
| Rate lock | At authorization, usually immediate | At network or issuer processing |
| Typical spread | 3%-12% practitioner range | Often lower, issuer-specific |
| Statement amount | Known in home currency | May change before posting |
| Customer control | Accepts merchant-side rate | Chooses network conversion route |
| Foreign transaction fee | May still apply | Card contract determines fee |
| Best use case | Fixed-budget reimbursement | Lowest-cost everyday spending |
Is DCC ever the better choice?
DCC can be rational when the exact home-currency amount has contractual or operational value greater than the likely markup. Examples include a corporate traveler who must reconcile a locked amount immediately, a prepaid budget with a hard ceiling, or a cardholder whose issuer applies an unusually expensive conversion fee.
The decision should be numerical. If a card charges a 4% issuer conversion fee and the DCC offer embeds 2%, DCC may be cheaper, but the cardholder must verify both figures and confirm that no additional foreign fee applies. A terminal’s “guaranteed rate” is not evidence that the rate is competitive.
DCC is usually a poor choice for ordinary purchases when the card has no foreign transaction fee. The predictable amount is then purchased at a premium that may exceed any plausible one-day exchange-rate movement.
How Do You Decline DCC Correctly?
Decline DCC by selecting the local currency option before authorization and checking the receipt afterward. The exact wording varies, but choices such as “pay in local currency,” “without conversion,” or “decline conversion” usually preserve the local-currency route.
- Read both amounts. Confirm which currency is local and which is the card’s home currency.
- Select local currency. Choose the option that leaves the charge in the destination country’s currency.
- Reject ambiguous prompts. Ask the cashier to cancel and restart if the screen shows only one currency.
- Check the receipt. Confirm that the transaction amount and currency match the local amount.
- Keep evidence. Photograph or retain the receipt when the prompt was unclear or the amount was unusually high.
- Review the statement. Compare the posted currency and amount with the receipt within the issuer’s dispute period.
A merchant may ask which currency the customer prefers, but the customer should make the selection directly whenever possible. Handing the terminal back without reading it creates a risk that the cashier selects the higher-cost option.
What if the merchant processes DCC without consent?
Ask the merchant to void the transaction and rerun it in local currency before leaving. If the merchant refuses, retain the receipt, record the date and terminal location, and contact the card issuer promptly with the claim that the currency choice was not properly authorized.
A chargeback is not guaranteed. The issuer will typically assess the receipt, transaction data, merchant evidence, network rules, and whether the customer entered a PIN or signed a clearly labeled currency choice. A vague complaint that the rate was expensive is weaker than evidence showing that the terminal did not present a choice or that the receipt contradicts the selected currency.
What Happens With Refunds, Tips, and Preauthorizations?
Refunds and adjustments can expose differences between the original DCC rate and the later transaction rate. A full refund may be issued in the original transaction currency, while the issuer or merchant applies a separate conversion process that does not recreate the original home-currency amount.
| Transaction situation | What may happen | Practical check |
|---|---|---|
| Full local-currency refund | Issuer converts the refund later | Compare original and refund currencies |
| Partial refund | Refund rate may differ from purchase rate | Calculate the refunded local amount |
| Hotel preauthorization | Temporary hold uses an estimated amount | Check final posted currency |
| Restaurant tip adjustment | Final amount changes after initial authorization | Confirm final receipt currency |
| Car-rental deposit | Hold may remain for days | Ask which currency controls release |
| Cancelled DCC purchase | Void may remove the original authorization | Verify the hold disappears |
Hotels, fuel stations, and car-rental companies often use preauthorizations. A DCC choice on the initial hold can affect the displayed home-currency amount, while the final charge may include taxes, tips, damage claims, or late adjustments.
Common Mistakes and Expert Rules
Mistake 1: Comparing only the displayed amounts
A home-currency amount feels easier to understand, but convenience is not the same as value. Compare the offered exchange rate with a reference rate from the card network, a reputable rate calculator, or the expected issuer conversion, allowing for the issuer’s disclosed fee.
Mistake 2: Assuming card denomination controls the result
A US-dollar card does not make a dollar-denominated merchant charge automatically cheap. DCC can convert euros into dollars at the merchant’s rate, and the issuer can still classify the merchant as foreign.
Mistake 3: Treating a locked rate as protection
A locked rate protects against later movement but does not protect against an unfavorable starting rate. A 7% markup exceeds ordinary short-term currency movement in many routine spending situations, although volatile currencies can move more sharply.
Mistake 4: Forgetting gratuity and final adjustments
The rate shown for a restaurant authorization may not be the rate economically experienced on a later tip adjustment or partial refund. Keep the local-currency receipt until the final statement posts.
Expert rule: use the card network when the issuer fee is low
For a card with a 0% foreign transaction fee, local currency is usually the financially conservative default. The cardholder accepts only ordinary settlement movement rather than a known merchant-side premium.
Expert rule: evaluate the whole ATM stack
A DCC-free withdrawal can still be expensive because of a fixed ATM fee, an issuer cash fee, and interest on a credit-card cash advance. Declining DCC solves one layer, not the complete withdrawal-cost problem.
Expert rule: large purchases magnify small percentages
On a $2,000 hotel bill, a 4% DCC spread costs about $80 before any separate issuer fee. Rate comparison matters more as the transaction value increases.
Alternatives to DCC
Travelers can reduce conversion uncertainty without accepting a merchant-side rate. The appropriate alternative depends on whether the priority is low cost, immediate budgeting, cash access, or account separation.
| Alternative | Conversion control | Typical cost pattern | Best fit |
|---|---|---|---|
| No-foreign-fee credit card | Network and issuer | 0% issuer fee plus network rate | Everyday card purchases |
| Multi-currency account | Account provider or stored balance | Provider spread varies | Frequent multi-country travel |
| Local cash withdrawal | Card network and issuer | ATM and issuer fees possible | Small cash-only purchases |
| Prepaid travel card | Provider rate or loaded balance | Load and conversion fees vary | Fixed travel budget |
| Local bank transfer | Bank or payment platform | Transfer fee and exchange spread | Larger planned payments |
| Merchant DCC | Merchant-side provider | 3%-12% typical spread | Immediate amount certainty |
Multi-currency accounts can be useful when the provider’s rate and fees are transparent, but they do not make every terminal choice irrelevant. A card linked to a euro balance may still receive a DCC offer in euros, and accepting it can bypass the account’s intended local-currency conversion.
Which Travelers Should Accept or Decline DCC?
| Traveler profile | Default decision | Reason | Exception |
|---|---|---|---|
| Leisure traveler | Decline DCC | Minimizes routine spending cost | Verified issuer fee exceeds DCC rate |
| Business traveler | Usually decline | Reduces expense leakage on large bills | Policy requires locked home currency |
| ATM user | Decline DCC | Avoids an extra conversion layer | Emergency access with no alternative |
| Online shopper | Keep merchant currency | Preserves network conversion | Provider’s published rate is demonstrably lower |
| Zero-fee cardholder | Decline DCC | Card benefit works through local currency | Unusual issuer or network pricing |
| Budget-constrained traveler | Compare both | Immediate certainty may matter | DCC amount stays below a hard limit |
Country-specific rules can affect how DCC is disclosed, but location does not make a poor rate competitive. The card issuer’s fee schedule, the merchant’s displayed markup, the transaction size, and the available currency options determine the financial result.
Frequently Asked Questions
Does DCC apply to debit cards?
Yes, DCC can apply to eligible debit cards when a foreign terminal or ATM recognizes the card’s issuing currency and supports the service. Debit cards may also have daily withdrawal limits, cash fees, or overdraft consequences, so rejecting DCC does not remove those separate account conditions.
Can I accept DCC with a no-fee travel card?
You can, but the card’s no-foreign-transaction-fee benefit may become irrelevant because the DCC provider sets the conversion rate. Compare the offered home-currency amount with the expected network conversion before accepting, especially for hotels, vehicle rentals, and other high-value authorizations.
Does declining DCC guarantee the lowest possible exchange rate?
No. Declining DCC generally avoids the merchant’s conversion spread, but the issuing bank may add a foreign transaction fee, use a network rate with its own spread, or apply a cash-advance charge. Review the card agreement and compare the complete cost rather than one rate alone.
How long does a local-currency card transaction take to post?
Many local-currency card transactions post within one to three business days, although weekends, offline terminals, preauthorizations, and merchant delays can extend the timeline. The final home-currency amount may differ from an estimate because conversion occurs during network or issuer processing.
Can a merchant force DCC?
A properly presented DCC transaction should provide a currency choice, but terminal procedures and local requirements vary. If a merchant processes home-currency billing without clear consent, request a void and rerun in local currency, then preserve the receipt and contact the issuer if the merchant refuses.
Is PayPal currency conversion the same as DCC?
PayPal’s conversion choice can resemble DCC because the customer may choose whether the merchant or PayPal converts the transaction. The contractual rate, disclosure, and account settings determine the exact process, so inspect the final currency and conversion details before confirming payment.
The Bottom Line
Dynamic Currency Conversion Explained in one rule: when a foreign terminal or website offers to convert a purchase into your home currency, choose local currency unless you have verified that the DCC rate and all issuer fees produce a better result. DCC provides immediate certainty, but its typical 3%-12% markup can outweigh that convenience, particularly on hotel bills, ATM withdrawals, and other large transactions.