How Hotel Incidental Deposits Work: Holds and Timing
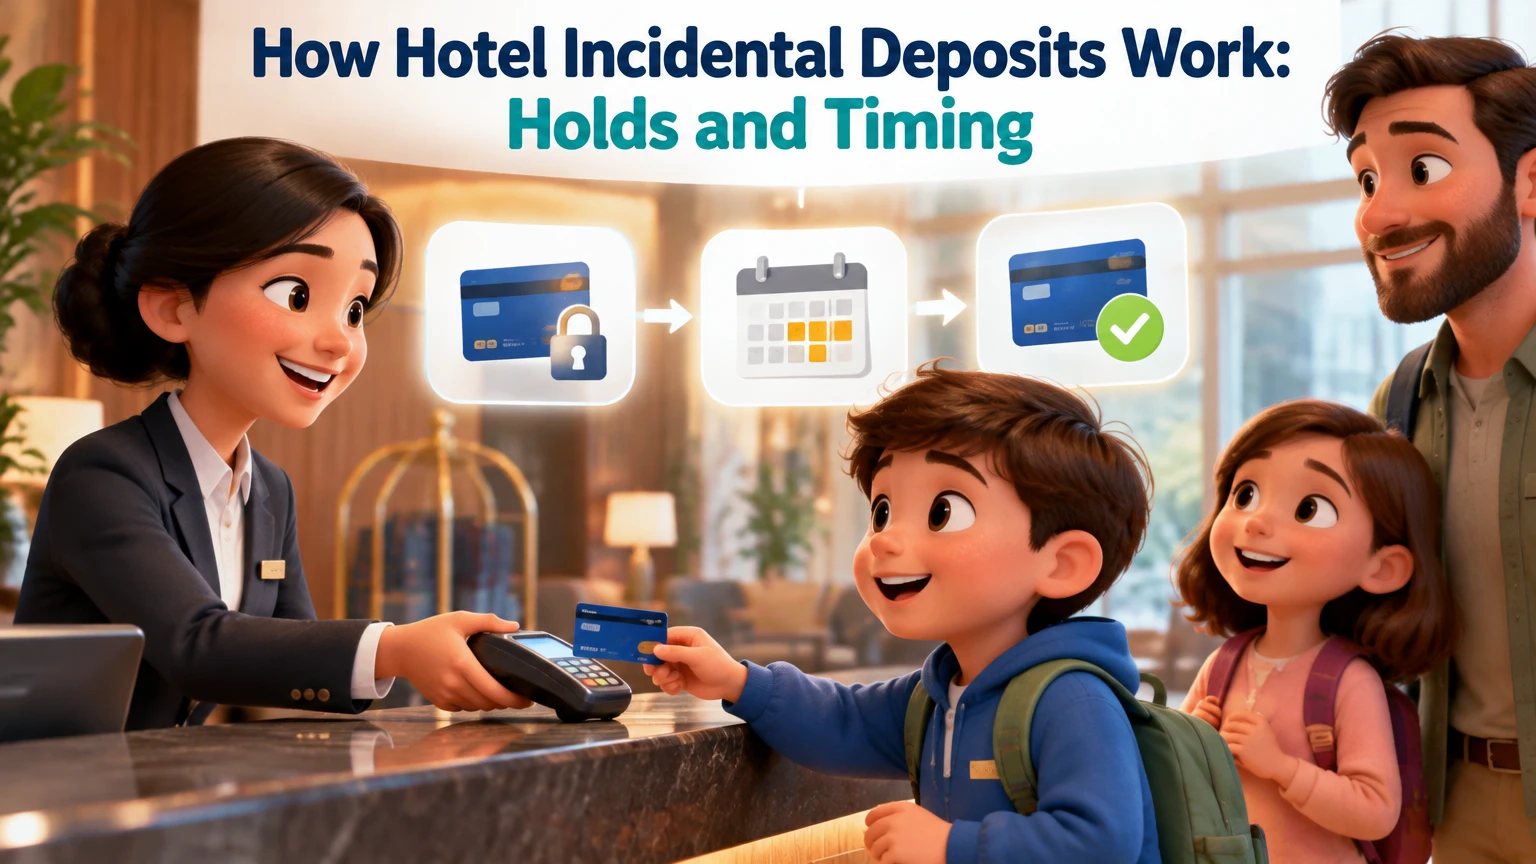
A hotel incidental deposit is a temporary authorization hold placed on a payment card at check-in to cover possible extra charges such as room service, minibar items, parking, damage, or missing property. The hold reduces available credit or available bank funds, but it is not normally a completed charge unless the hotel settles an incidental balance against it.
Key facts at a glance
A hotel incidental deposit is usually an authorization hold, not an immediate purchase.
Typical holds range from $50-$200 per night or $100-$300 per stay, depending on hotel policy.
Credit cards preserve checking-account cash, while debit cards temporarily restrict real funds.
A hotel can request an additional authorization if room charges exceed the original hold.
The hotel usually submits the release after checkout, but the bank controls when the pending amount disappears.
A prepaid reservation covers only the items included in the booking terms, not necessarily incidentals.
What Is a Hotel Incidental Deposit?
A hotel incidental deposit is a financial guarantee for charges outside the prepaid room rate. Hotels use it because a guest may consume minibar products, order food, use valet parking, damage property, or leave without settling the final folio.
The term “deposit” can be misleading. In many cases, the hotel does not take the money permanently at check-in. Instead, the property sends an authorization request through its payment processor, and the card issuer reserves that amount until the hotel completes or cancels the transaction.
The exact policy belongs to the individual property. A limited-service hotel may authorize $50 per night, while a resort may authorize $150-$250 per night because it offers restaurants, spa treatments, parking, and recreational services. Some hotels use a flat amount, while others combine the room balance, taxes, and estimated incidentals.
What does the deposit cover?
| Potential incidental | Typical posting point | Example amount | Usually charged to room? |
|---|---|---|---|
| Minibar beverage | During or after stay | $5-$25 | Yes |
| Room service meal | During stay | $20-$150 | Yes |
| Valet parking | Each night or checkout | $25-$100 per night | Often |
| Property damage | After inspection | $50-$2,000+ | Policy-dependent |
| Missing towel or item | After inspection | $10-$300 | Policy-dependent |
A hotel may also use the authorization to secure unpaid breakfast, resort fees, pet fees, late checkout, smoking remediation, or local telephone charges. The hotel’s registration agreement should identify these categories, although wording varies considerably.
How Does the Authorization Process Work?
A hotel incidental authorization normally follows six stages: reservation, check-in, hold placement, in-stay posting, checkout settlement, and release. The authorization amount is an available-funds reservation, so the guest can see less available credit or less spendable cash even when no final charge exists.
Stage 1: Reservation
The booking platform or hotel usually collects a card to guarantee the reservation. That card guarantee is different from the incidental hold. A hotel may also place a preauthorization for the room, particularly for nonrefundable bookings or same-day reservations.
Check the booking confirmation for separate phrases such as “pay at property,” “security deposit,” “incidentals,” “damage deposit,” and “resort fee.” A room prepaid through Expedia, Booking.com, or the hotel’s own website can still require a payment card at arrival.
Stage 2: Check-in
The front desk verifies identification, confirms the reservation, and asks for a payment method. The hotel then requests an authorization based on its policy, the length of stay, and sometimes the room category.
A typical calculation might look like this:
| Component | Example calculation | Amount |
|---|---|---|
| Room and tax already prepaid | Paid online | $0 due at arrival |
| Incidental authorization | $100 x 3 nights | $300 |
| Additional resort fee | $35 x 3 nights | $105 |
| Possible total authorization | Property-specific | $300-$405 |
The front desk should be able to tell you the amount before running the card. Ask whether the quoted figure is per night, per stay, or the combined room balance and incidental amount.
Stage 3: The hold reaches the card issuer
The hotel’s payment terminal sends the request through the card network to the issuing bank. If approved, the issuer reduces available credit on a credit card or available balance on a debit card.
The displayed pending amount can differ from the hotel’s verbal explanation because issuers may show the room authorization, incidental authorization, and completed room payment as separate entries. A pending entry is not equivalent to a posted purchase.
Stage 4: Charges accumulate
Guests can charge eligible purchases to the room. The hotel records those purchases in the folio, which is the account ledger for the stay.
If the initial authorization is $300 and the guest posts $180 in room service, parking, and minibar charges, the hotel may settle $180 against the authorization and release the unused $120. If the guest reaches or exceeds the original amount, the hotel may request another authorization.
Stage 5: Checkout settlement
At checkout, the front desk or back-office system reviews the folio. The hotel may charge a remaining balance, settle valid incidentals, and release the unused portion of the authorization.
Request an itemized folio showing room charges, taxes, incidental items, payments, and the final balance. A $0 balance proves the folio was settled, but it does not guarantee that the bank will remove a pending authorization immediately.
Stage 6: Bank processing
The hotel sends a release or completion message, but the card issuer determines when the pending amount disappears from the account. The hotel can often confirm that it released the hold, while only the bank can explain why the pending amount remains visible.
How Much Money Do Hotels Hold?
Hotel incidental holds typically range from $50-$200 per night or $100-$300 per stay, but resorts, luxury properties, extended stays, and hotels in high-cost cities can authorize more. The amount depends on the property’s risk policy, room category, length of stay, expected amenities, and whether the room balance is already paid.
| Hotel context | Typical incidental amount | Common pricing model | Main reason for variation |
|---|---|---|---|
| Limited-service hotel | $50-$100 per night | Per night | Fewer chargeable amenities |
| Full-service city hotel | $75-$150 per night | Per night or flat stay | Restaurant, parking, room service |
| Resort property | $100-$250 per night | Per night | Spa, recreation, multiple outlets |
| Luxury or suite hotel | $150-$300+ per night | Per night or custom | Higher damage and service exposure |
| Extended-stay property | $100-$500 per stay | Flat or weekly | Longer occupancy and furnishings |
These are typical practitioner ranges, not universal industry rules. A property can request a different amount, and some hotels describe a cash requirement as a “security deposit” even when card authorization is the normal process.
Does the hotel hold include the room price?
Sometimes. A hotel may authorize only incidentals when the room has been paid in full, or it may authorize the remaining room balance plus estimated incidentals when payment is due at arrival.
Ask this exact question before presenting the card: “What is the total authorization amount, and how much of it is for incidentals?” That wording separates the temporary guarantee from charges that the hotel intends to collect.
Which Payment Method Is Safest?
A credit card is usually the safest option for liquidity because it reserves credit rather than cash in a checking account. A debit card can work, but the hold can interfere with rent, transportation, meals, or emergency funds. Cash avoids bank-release delays only when the property accepts it and completes an inspection before returning it.
| Payment method | What becomes unavailable | Typical release period | Main risk |
|---|---|---|---|
| Credit card | Available credit line | 3-7 business days | Reduced credit for later spending |
| Debit card | Checking-account funds | 5-14 business days | Overdraft or cash-flow shortage |
| Cash | Physical money | Same day after inspection | Policy refusal or delayed inspection |
| Prepaid travel card | Loaded card balance | 5-30 days | Limited dispute and authorization support |
Credit card
A credit card separates the hotel hold from everyday cash. If the card has a $2,000 credit limit and the hotel authorizes $300, the available credit may fall to approximately $1,700 until the authorization is released or settled.
Use a card with enough unused credit for the entire trip. A $300 hotel hold can become a practical problem when a traveler also needs a $600 car-rental authorization and has only $750 available credit.
Credit cards are not automatically free from risk. A near-limit account may decline the hotel authorization, and a pending hold can reduce the credit available for an emergency purchase.
Debit card
A debit-card authorization affects the funds that the bank makes available for spending. Even when the hotel never posts an incidental charge, the checking account may show less available money until the issuer removes the pending authorization.
Debit cards create the greatest risk for travelers who budget tightly. A $400 hold can cause unrelated transactions to decline, trigger overdraft fees, or make an account appear lower than the posted ledger balance.
Cash
Cash can be useful when the hotel expressly accepts it and states the return procedure. Some properties require a cash deposit equal to a fixed amount, while others require the room balance plus a damage deposit.
Cash does not depend on a bank’s release process. However, staff may need to inspect the room before returning it, and many properties do not accept cash for incidentals or accept it only with a card on file.
When Is the Hold Released?
Hotels commonly initiate the release at checkout, while the card issuer may take 3-7 business days for a credit-card authorization and 5-14 business days for a debit-card authorization to disappear. Weekends, bank holidays, cross-border processing, issuer procedures, and unsettled hotel transactions can extend those typical windows.
| Situation | Hotel action | Typical visible result | Reason for delay |
|---|---|---|---|
| No incidentals | Release full authorization | Pending amount gradually vanishes | Issuer processing |
| $50 of incidentals | Complete $50, release remainder | One posted charge, lower pending amount | Settlement batching |
| Extra night added | Increase authorization | New or larger pending entry | Revised stay total |
| Checkout on weekend | Release after departure | Hold remains into following week | Non-business-day processing |
| International card | Send release in foreign transaction flow | Several days to several weeks | Cross-border issuer handling |
The release date and disappearance date are different events. The hotel may release the authorization on Monday, while the issuer removes the pending line on Wednesday.
Why is my hotel hold still pending?
A pending hold after checkout usually means the issuer has not processed the hotel’s release or the hotel has not completed its settlement message. Contact the hotel first if the folio is incorrect or the stay has not been checked out; contact the card issuer when the hotel confirms release and the pending amount remains beyond the quoted timeframe.
Use this escalation sequence:
- Save the checkout folio and the original authorization amount.
- Ask the hotel for the release date and authorization reference.
- Confirm whether any incidental charge was posted.
- Call the card issuer and ask about the pending merchant authorization.
- Provide the hotel name, transaction date, amount, and reference number.
- Escalate through the issuer’s dispute or complaints process if the authorization has expired or is unsupported.
Do not ask the bank to treat a legitimate posted charge as a pending hold. A posted charge requires a billing investigation or dispute, not an authorization-release request.
What Does the Deposit Cover?
The incidental deposit can cover room-related purchases, property damage, missing items, unpaid fees, and services charged to the room, but the exact categories depend on the registration agreement and local law. Hotels should not assume that every disputed amount is valid merely because an authorization was approved.
Common categories include:
- Minibar products and in-room snacks
- Room service and restaurant charges
- Parking, valet, and transportation services
- Spa, recreation, and entertainment charges
- Late checkout or unauthorized early arrival
- Smoking or excessive-cleaning fees
- Damage to furniture, fixtures, electronics, or linens
- Missing hotel property
- Pet-related cleaning or damage
An authorization does not give the hotel unlimited permission to charge any amount. The merchant still needs a contractual or factual basis for a posted charge, and the guest can request documentation when the amount is disputed.
What Happens If the Authorization Fails?
A failed authorization can prevent check-in until the guest provides another accepted payment method or resolves the card issue. Common causes include insufficient available credit, a debit-account restriction, an issuer fraud alert, an incorrect billing address, an expired card, or a hotel policy that rejects prepaid cards.
Before arrival:
- Check available credit, not just the credit limit.
- Check available checking-account funds, not just the ledger balance.
- Tell the bank about international travel when required.
- Confirm that the cardholder name matches the reservation requirements.
- Ask the hotel whether virtual cards, prepaid cards, or cash are accepted.
- Carry a second payment method with independent available funds.
If the hotel declines the card, ask for the exact authorization amount and whether a smaller authorization is possible. Do not repeatedly retry a card without understanding the failure, because multiple attempts can create several pending authorizations.
Can You Pay the Incidental Deposit in Cash?
You can pay a hotel incidental deposit in cash only when the property’s policy permits cash. Cash deposits often range from $100-$500 or equal a stated room amount, and the hotel may return the money after a manual inspection at checkout.
| Cash-deposit issue | Typical policy outcome | Guest action | Possible delay |
|---|---|---|---|
| Property accepts cash | Fixed deposit collected | Request written receipt | 0-30 minutes |
| Room inspection required | Staff checks room after departure | Wait at front desk | 15-60 minutes |
| Property rejects cash | Card required | Present accepted card | Same check-in |
| Damage discovered | Deposit partly retained | Request itemized explanation | Minutes to days |
| Night departure | Inspection unavailable | Refund may wait for staff | Next business day |
Cash is less useful for guests who need immediate departure, arrive after inspection staff leave, or stay at a hotel with strict card-only controls. Obtain a receipt that identifies the deposit amount, room number, date, and return condition.
What If the Hotel Claims Damage?
Ask for an itemized explanation, photographs, inspection notes, and the relevant registration-agreement clause before accepting a damage charge. A hotel may have a legitimate claim, but a vague statement such as “room damage” does not tell you what happened, when it happened, or how the amount was calculated.
Follow these steps:
- Request the final folio and damage assessment in writing.
- Ask when the room was inspected and by whom.
- Request photographs or repair and replacement documentation.
- Compare the claim with your check-in photos and messages.
- Explain factual errors briefly and attach evidence.
- Contact the card issuer if the hotel will not correct an unsupported posted charge.
Take timestamped photographs of expensive rooms, unusual furnishings, existing marks, and minibar contents at check-in. This practice is especially useful for suites, vacation rentals operated by hotels, and properties with high damage deposits.
How Do You Fix Incorrect or Duplicate Charges?
First distinguish pending authorizations from posted transactions. A pending authorization can disappear without a refund, while two posted transactions generally require correction by the hotel or a formal card dispute.
| Account display | Meaning | First contact | Correct response |
|---|---|---|---|
| One pending entry | Funds reserved temporarily | Hotel or issuer | Wait for release if folio is $0 |
| One posted incidental | Hotel completed a charge | Hotel accounting | Request itemization |
| Pending plus posted same amount | Possible normal settlement display | Issuer and hotel | Confirm whether pending will expire |
| Two posted identical charges | Potential duplicate billing | Hotel accounting | Request refund confirmation |
| Posted charge after disputed checkout | Possible damage or late fee | Hotel management | Request evidence and policy basis |
Keep the folio, receipt, emails, card statement, and checkout date. A clear timeline helps the hotel accounting team identify whether the apparent duplicate is a pending authorization paired with its final settlement.
What Should Different Travelers Do?
Budget travelers
Use a credit card with enough available credit for the hotel hold and keep debit-card funds available for food and transport. Confirm the hold before arrival when the daily budget is tight.
Business travelers
Calculate concurrent holds across all properties. Three hotels each placing a $250 authorization can restrict $750 of corporate-card availability even when the stays overlap by only a few days.
International travelers
Prefer a credit card with no foreign transaction fee and a sufficient limit. Currency conversion can make the final posted amount differ from the initial authorization, while cross-border release timing can exceed domestic expectations.
Guests using virtual or prepaid cards
Ask the hotel before arrival whether the card can support an incidental authorization. Some booking platforms issue virtual cards intended only for the room rate, leaving the guest responsible for a separate personal card at check-in.
Expert Rules That Prevent Most Problems
Rule 1: Ask for the total authorization, not the deposit alone. Front-desk staff may quote the incidental portion while the terminal also includes unpaid room charges and taxes.
Rule 2: Photograph the room before using amenities. A timestamped record is stronger than a memory when a hotel reports damage several days after departure.
Rule 3: Treat available credit as the binding limit. A card with a $5,000 limit can still decline a $300 hotel hold when existing pending transactions reduce available credit to $200.
Rule 4: Keep the final folio until the hold disappears. The folio proves the hotel’s account status, while the card statement proves whether the issuer removed or posted the authorization.
Hotel Incidental Deposit FAQ
Do hotels always require an incidental deposit?
No. Many hotels require a card authorization, but the amount and policy vary by property. Some limited-service hotels place a modest hold, some resorts use a larger nightly authorization, and some properties collect a separate cash or card damage deposit.
Can a hotel charge my debit card after checkout?
Yes. A hotel can post a valid incidental charge after checkout when the registration agreement permits it, such as for documented damage or an unpaid room-service item. Request an itemized explanation and supporting evidence if the charge is unexpected.
Does checking out early reduce the incidental hold?
Sometimes, but not automatically. The hotel may recalculate the authorization after shortening the stay, or it may leave the original hold until checkout settlement. Ask the front desk to confirm the revised amount and release any excess authorization.
Can someone else pay the hotel deposit?
Usually, but the hotel may require a credit-card authorization form, identification, or the cardholder’s presence. Policies differ for third-party cards, virtual cards, and prepaid reservations, so obtain approval before arrival.
Can I spend money while a hotel authorization is pending?
Yes, if enough available credit or bank funds remain. A pending authorization reduces the amount you can spend, so a traveler with a tight account may need to reserve funds for meals, transport, emergencies, and other pending transactions.
What should I do if the hotel will not release the hold?
Obtain written confirmation that the stay is closed and the authorization was released. Then contact the card issuer with the hotel’s release date and reference details. If the amount has posted rather than remaining pending, use the hotel’s billing process or the issuer’s dispute process.
The Bottom Line
How Hotel Incidental Deposits Work is straightforward: the hotel requests a temporary authorization, the card issuer restricts available credit or cash, and the hotel settles valid extras before releasing the unused amount. Use a credit card when possible, ask for the exact authorization, retain the final folio, and escalate delayed holds to the bank only after confirming the hotel released them.